Mortgage Rates Surge Ahead of CPI 2026: 6.85% Benchmark, 10-Year Treasury Yield Shock, and 5 Defensive Playbooks
(Advertisers wanted)
(Advertisers wanted)
📌 Topic & Subject
This article explores the surge in U.S. mortgage rates to a 15-month high of 6.85% in September 2026, driven by rising 10-year Treasury yields, inflation concerns ahead of the CPI release, and broader economic pressures. It examines the impact of these borrowing costs on home affordability, Treasury spreads, and household monthly payments using data from agencies like the Mortgage Bankers Association and Freddie Mac.
(Advertisers wanted)
(Advertisers wanted)
📌 Table of Contents
- 1. Executive Bottom Line: The 6.85% Benchmark and Why the 2026 Rate Surge Matters Today
- 2. Current Market Realities: Dissecting the 2026 Mortgage Benchmark Surge
- 3. The Engine of the Shock: Treasury Yield Spikes, $40T National Debt, and Energy Shocks
- 4. Comparative Data Matrix: Benchmark Rates, Spreads, and Historical Touchpoints
- 5. Structural Shifts in Loan Demand: Refinance Collapse and the ARM Resurgence
- 6. Strategic Evaluation: 5 Battle-Tested Defensive Playbooks for Homebuyers
- 7. Unveiling Insider Mechanics: The Traps, Trade-Offs, and Builder Hacks
- 8. Market Psychology and Social Sentiment: The Demise of "Marry the House, Date the Rate"
- 9. Expert Forecasts and CPI Scenarios: What the September 15–16 FOMC Means for Borrowers
The bottom-line reality for September 2026 is immediate and demanding: The 30-year fixed mortgage benchmark has jumped to a 15-month high of 6.85%, propelled by a violent breakout in the 10-year U.S. Treasury yield toward 4.979% and renewed inflation anxiety ahead of the August Consumer Price Index (CPI) release and the upcoming Federal Open Market Committee (FOMC) meeting. If you are shopping for a home, refinancing, or managing real estate exposure right now, the window of sub-6.5% borrowing costs that emerged earlier this year has closed. However, this does not mean capital deployment must freeze. By dissecting the underlying spread distortions, weighing the quantitative trade-offs between fixed and adjustable debt, and deploying structured financing mechanisms—from float-down locks to builder forward commitments—borrowers can defend their balance sheets against the current volatility shock. Let us pull up a chair, examine the raw metrics, and walk through exactly how the macro machinery is impacting your monthly payment.
1. Executive Bottom Line: The 6.85% Benchmark and Why the 2026 Rate Surge Matters Today
1.1 Core Takeaway: Navigating the 15-Month Peak Before September CPI
Financial markets rarely move in polite increments when macro anchors shift simultaneously. According to the Mortgage Bankers Association (MBA) for the week ending early September 2026, the benchmark contract interest rate for 30-year fixed-rate mortgages with conforming loan balances rose sharply to approximately 6.85%. This marks the highest borrowing benchmark recorded since June 2025, climbing 36 basis points above where the market stood twelve months ago. Simultaneously, Freddie Mac’s Primary Mortgage Market Survey (PMMS) registered its third consecutive weekly gain, landing at approximately 6.76% (up from 6.71% the week prior and 6.35% a year earlier), while real-time daily trackers from Mortgage News Daily and Bankrate printed prints fluctuating between 6.89% and 7.07% on intraday spikes, inclusive of an average 0.29 origination and discount points.
This rapid upward repricing is not an isolated mortgage anomaly; it is a direct pass-through from the sovereign debt market. The benchmark 10-year U.S. Treasury yield, which anchors residential debt securities, severed key resistance bands to surge from 4.79% to an intraday high of 4.979%—a technical territory not witnessed since November 2023. Ahead of the crucial August CPI inflation reading and the Federal Reserve’s September 15–16 rate decision, bond traders are systematically pricing in a persistent "higher-for-longer" baseline, compounded by fresh commodity price pressures and mounting sovereign debt issuance.
1.2 Real-World Household Impact: The Math Behind the $2,255 Monthly Shock
To understand what this means outside of trading terminals, we must translate basis points into monthly cash outflows. Consider the current baseline economic metrics published by federal agencies: the Department of Housing and Urban Development (HUD) projects the 2026 median family income at approximately $106,800, while National Association of Realtors (NAR) data places the median price of an existing single-family home at approximately $434,100.
Assuming a standard 20% down payment ($86,820), a buyer is financing a conforming principal balance of $347,280. Under Freddie Mac’s 6.76% benchmark, the monthly principal and interest (P&I) payment settles at about $2,255. That single payment consumes 25.3% of the median household's gross monthly income ($8,900), before property taxes, homeowner insurance, or private maintenance obligations are factored in. When evaluated under intraday quotes near 7.00%, that monthly payment expands toward $2,310. The velocity of this move has caught prospective buyers off-guard, effectively stalling transaction momentum and pushing debt-to-income (DTI) underwriting ratios to their upper limits.
2. Current Market Realities: Dissecting the 2026 Mortgage Benchmark Surge
2.1 MBA vs. Freddie Mac PMMS: Tracking the Ascent to 6.85% and 6.76%
When tracking mortgage metrics, evaluating the methodology of reporting institutions is essential. The MBA benchmark captures application-weighted contract rates across commercial banks, credit unions, and independent mortgage banks, which is why its 6.85% reading often registers volatility faster than survey-based metrics. Joel Kan, MBA’s Vice President and Deputy Chief Economist, plainly identified the drivers behind this move:
"Mortgage rates moved higher last week, driven by ongoing investor concerns over inflation and the federal budget deficit. The 30-year fixed rate increased to 6.85 percent, the highest since June 2025 and 36 basis points higher than a year ago."
Concurrently, Freddie Mac’s PMMS—which focuses on purchase-loan applications for prime borrowers putting 20% down—rose to 6.76%, while its 15-year fixed counterpart ticked up 5 basis points to 6.09% (compared to 6.04% the prior week and 5.50% a year ago). Robert Broeksmit, MBA President and CEO, noted the broader demand friction created by this trajectory:
"After dipping toward 5.98% earlier in the year, the 30-year fixed rate is testing the 6.85% threshold under pressure from international geopolitical disruptions and elevated energy costs. While underlying homebuyer demand exists, this rate shock continues to delay purchase contract signings across key metropolitan regions."
2.2 Daily Volatility and the Psychological 7.00% Resistance Barrier
In the primary broker channels, retail mortgage rate sheets have exhibited extreme intra-day swings. Average loan pricing captured by Mortgage News Daily showed headline conforming quotes brushing 6.89%, while lenders without secondary market trading cushions quoted standard 30-year fixed notes at 7.05% to 7.07% for borrowers with credit scores below 720.
Refinance pricing sustained an even steeper blow: the 30-year fixed refinance rate jumped approximately 34 basis points in a single week to 7.31%, while the 15-year fixed refinance average climbed to 6.22%. In the government-backed sector, Federal Housing Administration (FHA) 30-year fixed programs held somewhat steadier at 6.567%, while 30-year Jumbo balances hovered near 6.74%. The return of the 7.00% figure represents a severe psychological threshold for consumer sentiment, freezing discretionary market participants in place.
3. The Engine of the Shock: Treasury Yield Spikes, $40T National Debt, and Energy Shocks
3.1 The 10-Year Treasury Vault: Breaking Through 4.79% to 4.979%
To grasp why mortgage lenders altered their rate sheets overnight, one must look at the U.S. 10-Year Treasury bond. Residential mortgages are rarely held for their full 30-year maturity; voluntary payoffs, property sales, and refinancings condense the effective duration of mortgage-backed securities (MBS) to an average lifespan of roughly 7 to 10 years. As a result, mortgage yields track the 10-year Treasury yield with high fidelity.
Between late August and the second week of September 2026, the 10-year Treasury yield underwent a dramatic repricing, vaulting from approximately 4.79% through intermediate resistance at approximately 4.88%, before touching intraday peaks between approximately 4.92% and 4.979%. This constitutes a structural breakout to levels unseen since November 2023. Fixed-income investors demanded higher risk premia across all tenors, triggered by a confluence of fiscal supply overhang and firm macroeconomic indicators.
3.2 Oil at $100, Deficit Expansion, and the Fed's Looming Dilemma
Three sovereign catalysts converged to spark this yield spike:
- Energy Price Resurgence: Escalating Middle East geopolitical tensions interrupted global maritime distribution corridors, driving Brent Crude and WTI futures back above the $100-per-barrel threshold. Concurrently, U.S. retail diesel prices surged toward $6.00 per gallon, reintroducing freight and logistics costs into core consumer supply chains and lifting August headline CPI projections toward 3.4% year-over-year.
- Fiscal Debt Expansion: Total U.S. national debt officially eclipsed $40 trillion in 2026. The Department of the Treasury's quarterly refunding schedules have flooded the primary market with high-volume debt issuance, encountering softened bid-to-cover ratios from international reserve managers.
- Aggressive Repricing of Fed Expectations: Following robust non-farm payroll and wage metrics, CME FedWatch probabilities executed a dramatic pivot. Earlier baseline assumptions of sustained policy pauses or rate cuts evaporated; derivatives pricing surged to reflect a probability range of approximately 60% to 86.5% for a 25-basis-point "hawkish step" by the Federal Reserve at its September 15–16 FOMC meeting.
4. Comparative Data Matrix: Benchmark Rates, Spreads, and Historical Touchpoints
To evaluate these shifts systematically, we have compiled an exhaustive technical matrix contrasting prevailing interest rate products, historical markers, and macro yield spreads as of September 2026.
| Metric / Loan Specification | Current Benchmark (Sept 2026) | Prior Week | Year-Ago Level (Sept 2025) | Historical Context & Comparison |
|---|---|---|---|---|
| 30-Year Fixed (MBA Benchmark) | 6.85% | 6.79% | 6.49% (+36 bps) | Highest print since June 2025 (15-month peak) |
| 30-Year Fixed (Freddie Mac PMMS) | 6.76% | 6.71% | 6.35% | Third straight week of gains; June 26, 2025 high |
| 15-Year Fixed Conforming | 6.09% | 6.04% | 5.50% | Offers 67 bps spread relief vs. 30-year fixed |
| 5/1 Adjustable-Rate Mortgage (ARM) | 5.82% | 5.94% | 6.11% | Declined 12 bps WoW; spread vs. 30Y widened to 103 bps |
| 30-Year Refinance Average | 7.31% | 6.97% | 6.82% | Surged 34 bps WoW; Refinance Index down -25% YoY |
| FHA 30-Year Fixed | 6.567% | 6.490% | 6.210% | Appeals to lower-credit/FICO tiers; annual MIP applies |
| 10-Year U.S. Treasury Yield | 4.920% – 4.979% | 4.790% | 4.280% | Highest level since November 2023; testing 5.00% |
| Mortgage-to-Treasury Spread | 190 – 210 bps | 192 bps | 207 bps | Structurally elevated vs. 150–180 bps historical norm |
| Brent Crude Oil (USD/bbl) | > $100.00 | $88.40 | $74.50 | Geopolitical supply disruption fueling headline CPI fears |
4.1 Spread Blowout: Why the 190–210 bps Gap Defies Historical Norms
One of the most critical structural insights for borrowers is that current high mortgage rates are not merely a reflection of the Federal Reserve’s policy stance. Historically, the spread between the 10-year Treasury yield and the 30-year fixed mortgage rate typically averages between 150 and 180 basis points (1.50% to 1.80%).
Today, that spread remains dislocated at 190 to 210 basis points. Why? Because the Federal Reserve is executing Quantitative Tightening (QT), running off its massive balance sheet of agency mortgage-backed securities without reinvesting the proceeds. At the same time, commercial banks face heightened liquidity regulations, limiting their appetite to absorb MBS paper. As a consequence, private asset managers demand an additional 40 to 50 basis points of yield buffer to hold mortgage debt. This structural "spread blowout" directly penalizes the borrower, representing roughly $110 to $140 per month in additional financing costs on a $400,000 balance beyond standard macroeconomic risks.
4.2 2021 Pandemic Lows vs. 2023 Peak vs. September 2026 Reality
To grasp the cumulative erosion in affordability, evaluate the trajectory of a standard $400,000 principal balance across three key eras:
- January 2021 Pandemic Trough (2.65%): The monthly principal and interest payment stood at $1,612.
- October 2023 Peak (7.79%): The monthly payment spiked to an all-time high of $2,877.
- September 2026 Current Benchmark (6.85%): The monthly payment is $2,621.
While borrowing costs have pulled back 94 basis points from the severe 2023 peak, payments remain approximately $1,009 per month (+62.6%) higher than the 2021 trough on the exact same debt load. When matched with home prices that gained over 30% nationally across that multi-year cycle, housing affordability remains near modern historical lows.
5. Structural Shifts in Loan Demand: Refinance Collapse and the ARM Resurgence
5.1 The 25% Refinance Contraction and Market Paralysis
Lenders across the country are navigating what capital markets describe as "rate paralysis." According to MBA application volume for the week ending September 4, 2026, total mortgage application volume fell approximately 2.7% week-over-week. The Refinance Index dropped 6% over the same weekly interval, descending to its lowest level since May 2025 and posting a 25% year-over-year collapse. Refinancing transactions now represent just 40.9% of total mortgage activity, largely limited to cash-out consolidation of high-interest consumer revolving credit.
The Purchase Index slipped a modest 0.2% on the week, though it maintains a fragile 4% positive differential relative to the same period in 2025. This resilience indicates that demographic household formation—millennials reaching peak family planning and life transitions—continues to generate baseline transactional demand despite unfavorable borrowing costs.
5.2 The 103 bps Spread Advantage: The Mathematical Appeal of the 5/1 ARM
In response to conforming fixed rates rising toward 6.85%, institutional data reveals a sharp shift in borrower product selection. While fixed rates marched higher, the benchmark 5/1 Adjustable-Rate Mortgage (ARM) dropped 12 basis points to 5.82%. This widened the spread between 30-year fixed debt and initial ARM pricing to 103 basis points (1.03 percentage points).
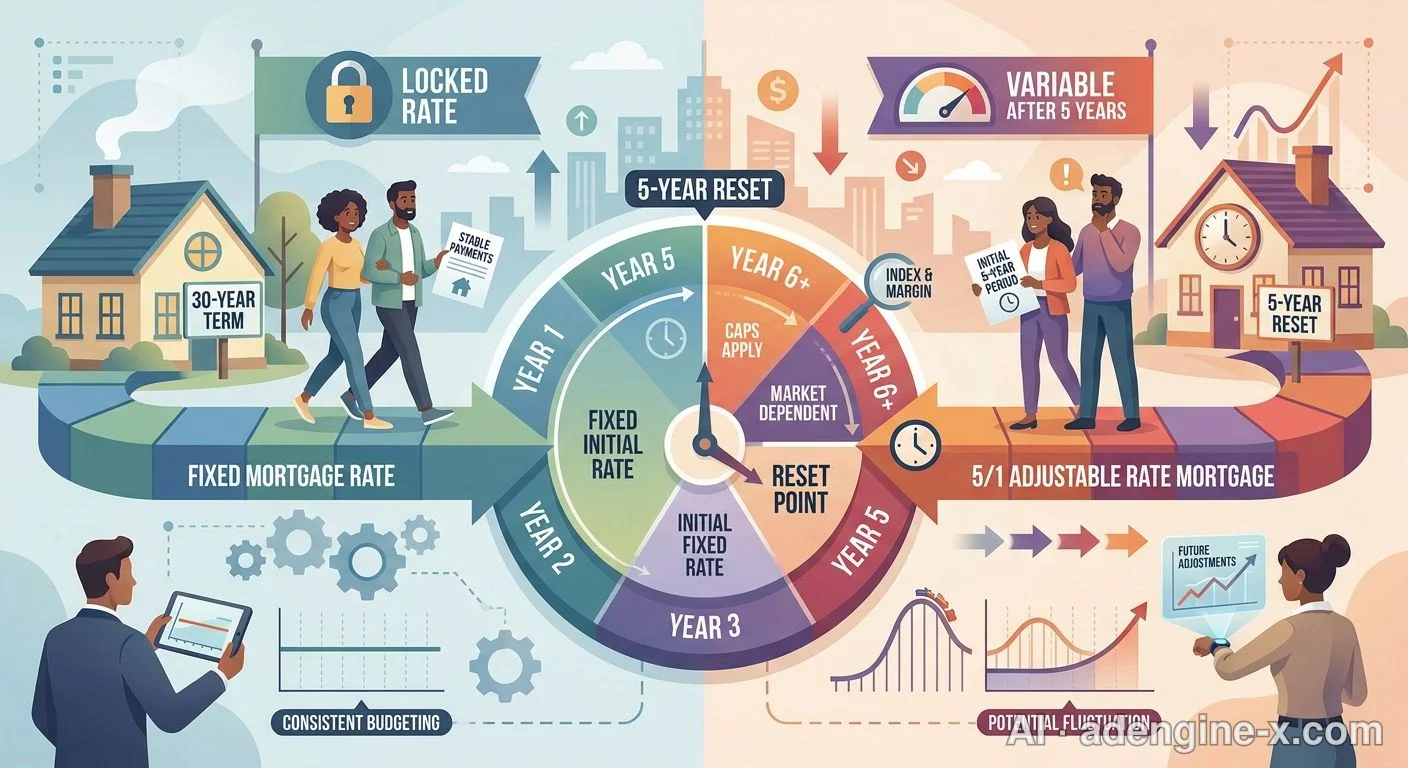
Predictably, the ARM share of total loan applications climbed to 8.5%, establishing a summer 2026 high. On a $400,000 mortgage:
- The 30-year fixed loan at 6.85% requires $2,621 monthly.
- The 5/1 ARM at 5.82% requires $2,352 monthly for the initial 60-month window.
- Net Monthly Cash Flow Differential:$269 savings per month, totaling $16,140 in cash preserved over the initial five-year holding period.
However, this strategy carries trade-offs. If benchmark interest rates fail to decline prior to month 61, the borrower faces rate resets tied to the Secured Overnight Financing Rate (SOFR) plus a predetermined margin, introducing payment volatility if macro yields remain sticky.
6. Strategic Evaluation: 5 Battle-Tested Defensive Playbooks for Homebuyers
Navigating a 6.85% environment requires executing active tactical playbooks rather than accepting retail pricing passively. Below are five proven strategies designed for current debt capital conditions.
6.1 Playbook 1: The Float-Down Rate Lock Protocol
With CPI prints and FOMC announcements introducing intraday price dispersion, executing an unhedged rate lock carries two-sided risk: locking immediately leaves you exposed if yields drop post-meeting, while floating unhedged exposes you to a sudden spike past 7.00%.
- Execution Mechanism: Secure an upfront 45-to-60-day Rate Lock that formally includes a written "Float-Down" provision. This contractual feature locks in your current ceiling rate today. If the 10-year Treasury yield rallies post-CPI and lender pricing improves by a defined threshold (typically 25 basis points), you maintain the unilateral right to reset your contract rate lower before underwriting completion.
- Operational Parameters: Lenders charge between 0.125% and 0.25% of the loan amount for this option, though several retail lenders waive this cost in competitive markets. Ensure the float-down criteria are clearly documented on your official Loan Estimate.
6.2 Playbook 2: Strategic 5/1 or 7/1 ARM Switching Under Duration Discipline
With the fixed-to-adjustable spread exceeding 100 basis points, ARM structures offer effective interest expense management—provided your personal timeline matches the reset schedule.
- Candidate Profile: Corporate professionals anticipating relocations, buyers purchasing transitional starter properties, or households planning career moves within a 5-to-7-year window.
- Risk Mitigation Discipline: Never underwrite an ARM based solely on the hope of refinancing before the reset date. Verify that your household cash flow can support the contract's lifetime maximum cap (often 5% above the start rate, or 10.82% in this case) in the event of an adverse macroeconomic cycle.
6.3 Playbook 3: Seller-Concession 2-1 Temporary Buydowns
In an environment where properties are staying on the market longer, requesting a price discount of $15,000 to $20,000 often yields negligible monthly savings (approximately $80 to $100 per month). Directing those funds toward a 2-1 Temporary Buydown delivers significantly higher near-term value.
- How It Operates: The seller provides a concession (typically 2% to 2.5% of the purchase price) deposited directly into an escrow account at closing. During Year 1, your note rate is reduced by 2.00% (4.85%). In Year 2, it is reduced by 1.00% (5.85%). In Year 3 through 30, it reverts to the permanent note rate of 6.85%.
- Cash Flow Advantage: On a $400,000 loan, your Year 1 payment drops from $2,621 to $2,111—saving $510 per month ($6,120 annually). This provides immediate financial flexibility during the initial home settlement phase.
6.4 Playbook 4: FHA Transition Coupled with Down Payment Assistance (DPA)
For buyers with credit scores between 640 and 720, conventional financing at 6.85% imposes punitive risk-based pricing adjustments (LLPAs). Transitioning to an FHA-insured loan can often improve headline borrowing terms.
- Rate Mechanics: Prevailing FHA 30-year fixed rates sit near 6.567%, a 28-basis-point discount to conventional paper. Furthermore, FHA guidelines permit higher debt-to-income limits and lower down payments (3.5%).
- The Trade-Off: FHA loans require an Upfront Mortgage Insurance Premium (UFMIP) of 1.75% plus an annual Mortgage Insurance Premium (MIP) of approximately 0.55% that remains for the life of the loan. Run a comprehensive Annual Percentage Rate (APR) comparison against conventional private mortgage insurance (PMI) to confirm total cost advantages.
6.5 Playbook 5: Hunting Assumable Low-Rate Government Mortgages
The single most powerful financing hedge in a high-rate environment is assuming an existing government-backed loan originated during the pandemic era.
- The Setup: FHA, VA, and USDA loans feature statutory clauses that allow the mortgage to be assumed by an eligible buyer at the original note rate (often between 2.50% and 3.50%).
- The Execution Challenge: If a seller owes $280,000 on a 2.75% VA loan on a home selling for $430,000, the buyer must bridge the $150,000 equity gap via cash reserves or a subordinate second mortgage (such as a Home Equity Line of Credit or HELOAN). Where capital allows, acquiring an in-place 2.75% mortgage creates an unmatched long-term financing advantage.
7. Unveiling Insider Mechanics: The Traps, Trade-Offs, and Builder Hacks
7.1 The Discount Point Illusion: Why Paying Upfront Capital Is a High-Risk Gamble
When quotes hover near 7.00%, loan originators routinely present pricing sheets showing rates at 6.375% or 6.500%. Scrutinize the fine print: this nearly always involves purchasing 1.5 to 2.0 "discount points" (upfront prepaid interest).
On a $400,000 loan, 2 discount points require paying $8,000 in cash at the closing table to lower the rate from 6.85% to 6.35%. This reduces the monthly principal and interest payment from $2,621 to $2,489—a savings of $132 per month. Calculating the break-even horizon:
Break-Even Period = $8,000 Upfront Cost ÷ $132 Monthly Savings = 60.6 Months (5.05 Years)
If macroeconomic adjustments or Federal Reserve shifts allow you to refinance, or if you sell the property within five years, those upfront funds are permanently lost. In a late-cycle, volatile yield environment, paying heavy discount points is often an inefficient allocation of capital.
7.2 New Construction Subsidies: Builder Forward Commitments at 4.99%
While existing home sellers face structural limitations on financing flexibility, publicly traded national homebuilders (e.g., Lennar, D.R. Horton, PulteGroup) operate under different capital dynamics. Utilizing captive mortgage subsidiaries, builders execute bulk "forward commitments" with institutional secondary investors.
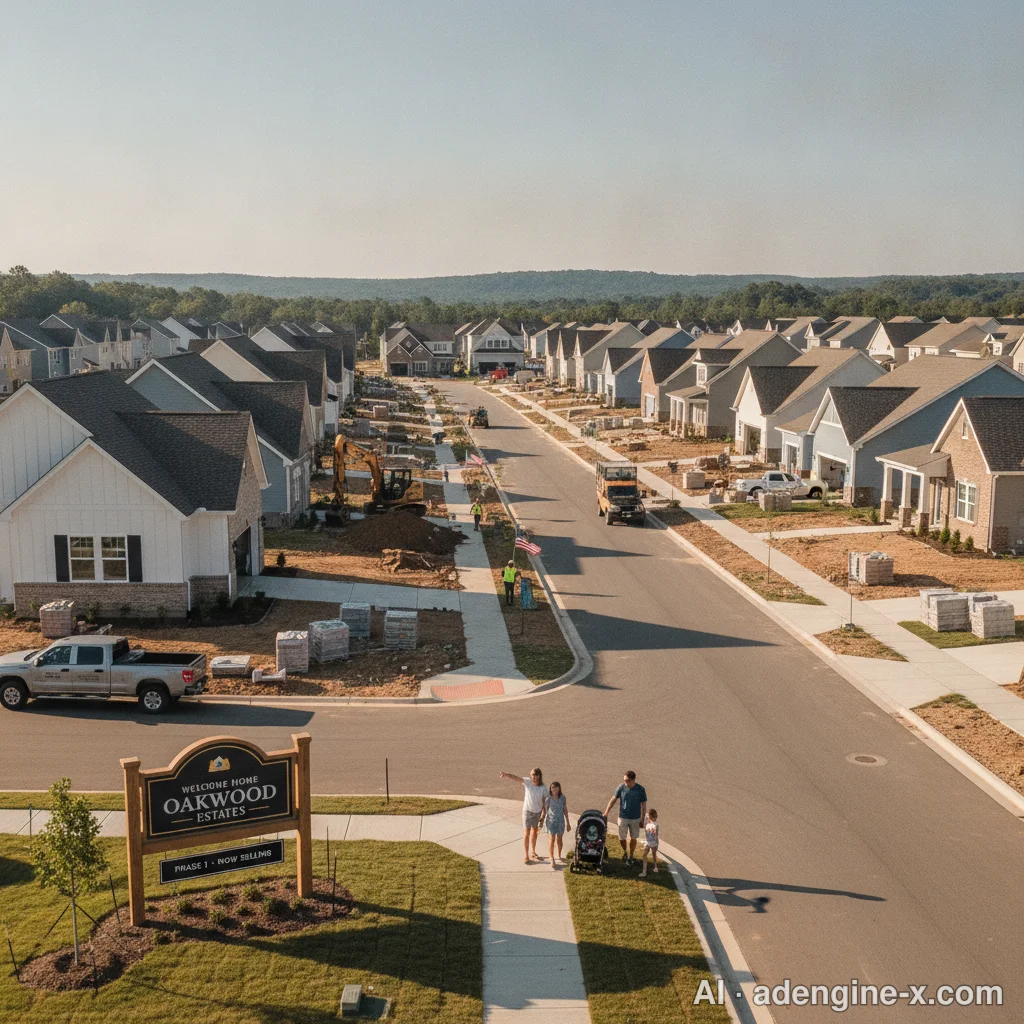
By pre-purchasing multi-million-dollar blocks of mortgage origination capacity ahead of rate spikes, these builders routinely advertise 30-year fixed financing rates between 4.99% and 5.50% on standing inventory. For buyers feeling priced out of the resale market, exploring new construction inventory with builder-subsidized debt can offer a direct route to sub-6.00% financing without requiring secondary seller negotiations.
8. Market Psychology and Social Sentiment: The Demise of "Marry the House, Date the Rate"
8.1 Rate Fatigue and the Sentiment Shift in Online Communities
The psychological toll of persistent borrowing friction is evident across consumer sentiment indicators. The CNN Fear & Greed Index has slipped from 36.3 to 31.2, entering "Fear" territory alongside declines in equity benchmarks (Dow -0.60%, S&P 500 -0.58%, Nasdaq -0.65%).
On active retail housing forums such as Reddit’s r/RealEstate and r/FirstTimeHomeBuyer, the prevailing sentiment is characterized by acute "rate fatigue." Prospective buyers who watched rates briefly pull back toward 6.0% earlier in 2026 express frustration at being priced out once again. The long-standing real estate marketing slogan—"Marry the house, date the rate"—has met growing skepticism. Homebuyers recognize that if structural inflation and $40 trillion in national debt keep the 10-year Treasury yield pinned above 4.50%, low-cost refinancing opportunities may not materialize on an accelerated timeline.
8.2 Loan Officer Playbooks in a Frozen Resale Landscape
Mortgage loan originators are fundamentally restructuring their daily operations. With vanilla refinance volumes down 25% year-over-year, originating professionals are focusing on debt restructuring strategies, pairing home purchase consultations with home equity second-lien payouts to retire 22% revolving credit card balances.
Sam Khater, Freddie Mac’s Chief Economist, emphasized the value of shopping across multiple lenders during volatile periods:
"Treasury yield volatility continues to challenge prospective home buyers. In an environment characterized by wide pricing variations between balance sheets, consumers can secure substantial lifetime savings simply by obtaining multiple formal Loan Estimates rather than defaulting to a single financial institution."
9. Expert Forecasts and CPI Scenarios: What the September 15–16 FOMC Means for Borrowers
9.1 Scenario A vs. Scenario B: The Inflation Print Binary Outcome
All eyes in institutional debt capital markets are locked on the upcoming August CPI release. Analysts broadly outline two distinct short-term trajectories heading into the September 15–16 FOMC meeting:
- Scenario A: Hot CPI Print (Headline YoY > 3.5%)
If energy pass-through and shelter metrics lift annual CPI above 3.5%, bond yields will face renewed upward pressure. The 10-year Treasury yield would likely test the psychological 5.00% ceiling, pushing benchmark 30-year conforming mortgage rates into the 7.00% to 7.25% range. This outcome would further constrain autumn transaction volume, forcing additional price concessions across inventory-heavy markets. - Scenario B: In-Line or Subdued CPI Print (Headline YoY ~3.3%–3.4%)
If core services cool and headline metrics align with consensus forecasts, the market could see a tactical relief rally. A stabilization in bond markets could guide 10-year Treasury yields back toward 4.60%–4.70%, allowing 30-year mortgage rates to settle into a 6.50% to 6.65% range.
Melissa Cohn, Regional Vice President at William Raveis Mortgage and a 44-year industry veteran, offers a compelling contrarian perspective on how market expectations may play out:
"Market dynamics can behave counterintuitively. Paradoxically, if the Federal Reserve adopts a resolute stance at the September FOMC to confront resurgent inflation, institutional bond investors may gain confidence that price stability will be preserved over the long run. That policy credibility can ease inflation risk premiums, paving the way for long-term Treasury yields and mortgage rates to stabilize or pull back."
9.2 Year-End Trajectories: Acknowledging the New Structural Normal
Looking past the immediate September meeting, major housing agencies—including Fannie Mae and the MBA—have revised their year-end 2026 mortgage rate projections into a narrower range of 6.60% to 6.80%. Corey Burr, Senior Vice President at TTR Sotheby’s International Realty, highlights the extent to which current risks are already integrated into pricing:
"The solid August labor market data and oil pushing past $100 per barrel have cemented a hawkish policy baseline for the Fed's September deliberations. Much of this friction is already priced into prevailing 6.8% to 6.9% mortgage sheets; whether the national average decisively breaches 7.0% will depend on the forthcoming CPI print."
Matt Schulz, Chief Financial Analyst at LendingTree, reinforces the importance of setting clear expectations for household balance sheets:
"Hoping for a sudden return to sub-6% mortgage rates in the near term is fundamentally unrealistic. The pandemic-era baseline of 2% to 3% borrowing is behind us. Consumers must evaluate their financial capacity based on current market realities and structure their personal finances around a persistent higher-rate environment."
Financial & Underwriting Disclosure: Specific loan eligibility, pricing tiers, annual percentage rates (APR), and structural underwriting conditions are strictly subject to individual loan disclosures, verified borrower credit profiles, property appraisals, lender underwriting determinations, and official public guidelines. This market review is prepared for informational purposes only and does not constitute formal legal, accounting, tax, or mortgage lending advice.
ℹ️ This article was drafted with the help of an AI tool and reviewed/edited by a human before publishing. · Original: AdEngine-X
📚 References
This list may include both live search sources the AI referenced while writing and public-data sources checked during fact verification. Please verify the original sources before citing or reusing.
0 Comments
Loading comments...