Tesla Delivery Surprise vs. Automotive Margin Realities
(Advertisers wanted)
(Advertisers wanted)
📌 Topic & Subject
This article examines Tesla's third-quarter 2026 vehicle deliveries and production figures, which exceeded analyst consensus and drove a stock price rally. It specifically discusses the company's inventory drawdown, energy storage deployments, and macroeconomic factors influencing electric vehicle demand, while highlighting ongoing debates regarding vehicle profitability and upcoming financial results.
(Advertisers wanted)
(Advertisers wanted)
📌 Table of Contents
- 1. Third-quarter operational figures confirm inventory drawdown
- 2. Operational metrics across reporting periods
- 3. Macro tailwinds support delivery execution
- 4. Profitability tests loom behind delivery totals
- 5. Capital commitments dictate long-term valuation
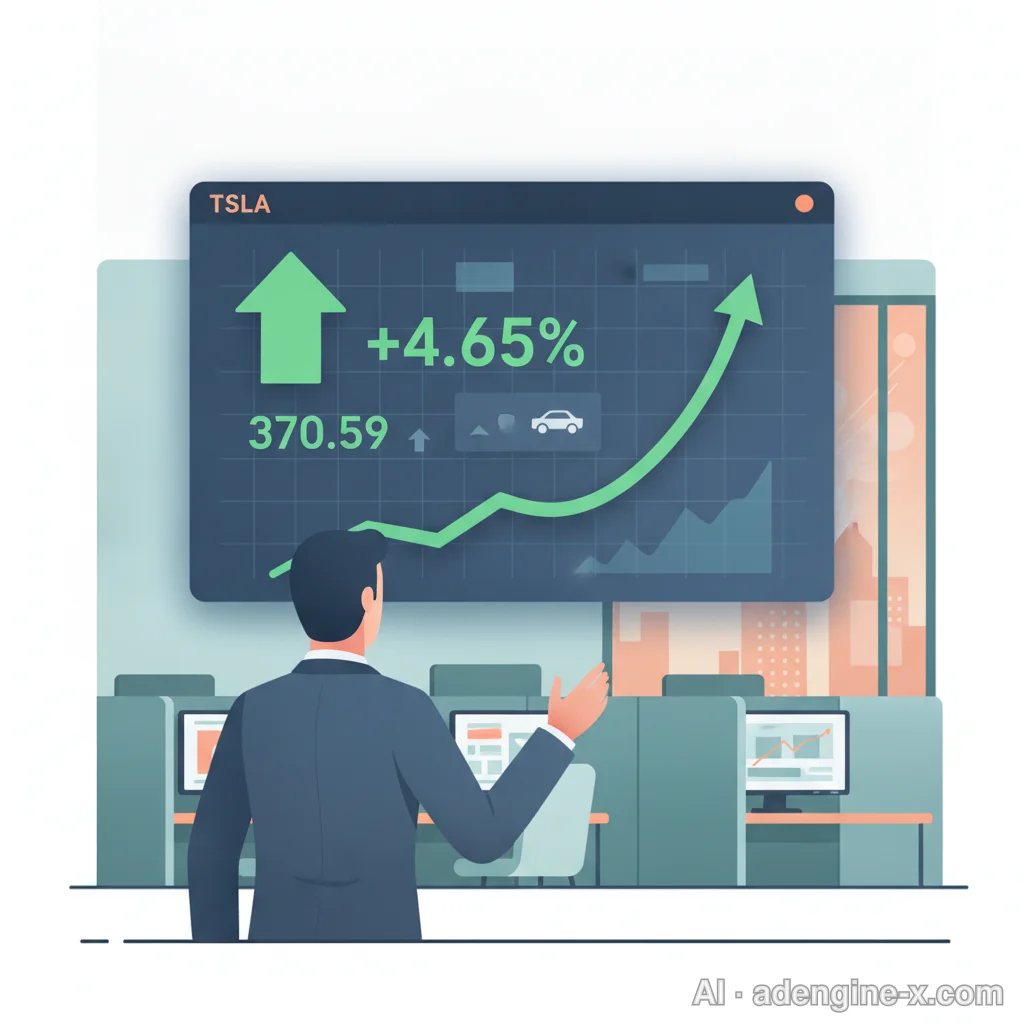
Tesla closed at approximately $370.59, gaining about 4.65% over its previous close of $354.11 on heavy trading volume. The rally followed third-quarter vehicle deliveries of approximately 486,532 units, beating the company-compiled consensus of around 461,974 units.
Key takeaways:
- Third-quarter deliveries reached 486,532, beating analyst consensus by 24,558 units.
- Inventory cleared 22,141 units as deliveries exceeded quarterly production.
- October 21 financial results determine if discounts hurt automotive gross margins.
Third-quarter operational figures confirm inventory drawdown
Tesla produced approximately 464,391 vehicles and delivered about 486,532 units during the third quarter of 2026. Deliveries cleared the company-compiled consensus of around 461,974 units by approximately 5.3% while trailing peak 2025 volumes by about 2.1%. The operational spread between production and deliveries reveals that existing inventory supplied 22,141 vehicles toward customer handoffs. Without inventory liquidation, factory output alone would have cleared consensus expectations by roughly 2,417 vehicles.
Core Model 3 and Model Y units constituted approximately 478,237 deliveries, accounting for about 98.3% of vehicle throughput. The remaining portfolio, consisting of Cybertruck, Model S, and Model X, reached approximately 8,295 units, contracting about 47.9% year-over-year. Energy storage deployments recorded approximately 13.7 GWh, advancing above the prior-year benchmark of about 12.5 GWh yet missing certain institutional projections of around 15.9 GWh. Overall delivery volumes outpaced bears who anticipated severe summer demand deterioration across major automotive markets.
The gap between manufacturing runs and sales tallies signals deliberate balance-sheet optimization before model updates. Working down 22,141 units effectively balanced total output against cumulative customer intake across the calendar year. Production through three quarters stands at approximately 1,324,535 units against deliveries of about 1,324,681 units, representing a tight net discrepancy of around 146 vehicles. The underlying liquidation confirms that factory efficiency remained aligned with retail orders without worsening idle parking lot capacity.
Operational metrics across reporting periods
| Metric Category | Q3 2026 Actual | Consensus / Baseline | Variance / Comparison |
|---|---|---|---|
| Total Vehicle Deliveries | 486,532 units | 461,974 units | +5.3% vs. consensus |
| Total Vehicle Production | 464,391 units | 486,532 deliveries | -22,141 units (inventory drawdown) |
| Model 3 / Model Y Deliveries | 478,237 units | 481,166 units (Q3 2025) | -0.6% year-over-year |
| Other Models Deliveries | 8,295 units | 15,933 units (Q3 2025) | -47.9% year-over-year |
| Energy Storage Deployment | 13.7 GWh | 12.5 GWh (Q3 2025) | +9.6% year-over-year |
| Year-to-Date Total Deliveries | 1,324,681 units | 1,217,902 units (YTD 2025) | +8.8% year-over-year |
Macro tailwinds support delivery execution
Broader equity strength amplified market reactions to the delivery beat. Trading volume reached 55,330,098 shares, exceeding the 20-day average volume benchmark of 38,120,430 shares by 45.1%. The Nasdaq 100 Index advanced 1.00% during the session, lifted by easing rate hike expectations following weak employment data. Tesla rallied off its session low of $359.41 toward an intraday high of $374.60 before stabilizing above $370.00.
Elevated fuel prices driven by Middle Eastern geopolitical instability created additional consumer interest in electric mobility alternatives according to commentary from CNBC contributor Jim Cramer. Rising retail gasoline costs typically shorten customer payback calculations when evaluating ownership expenses against internal combustion engines. Consumer interest also leaned on low-interest financing promotions that lowered initial barriers across North American and European regional networks. The resulting sales momentum allowed retail deliveries to outpace pessimistic estimates that anticipated double-digit drops.

Automakers face diverging operational outcomes under identical macroeconomic crosscurrents. Rivian delivered 19,248 units in the same reporting cycle, achieving a quarterly production high. Yet its stock declined on persistent cash burn and component shortages, highlighting differing tolerance for corporate liquidity profiles. Tesla demonstrated profitable scale by sustaining volume while clearing inventory, generating an equity response that added tens of billions to market capitalization.
Profitability tests loom behind delivery totals
Headline delivery numbers do not disclose vehicle profitability. Delivery tallies treat discounted inventory sales identically to full-price premium trims, masking underlying revenue realization per unit. Tesla utilized interest rate subsidies, aggressive financing structures, and leasing reductions throughout August and September to clear vehicle lots. Investors must weigh headline volumetric recovery against the likelihood of automotive margin contraction excluding regulatory credit windfalls.
Sell-side analysts caution that delivery volume alone cannot settle the valuation debate. Research analysts from Oppenheimer & Co. maintained a Perform rating on the stock following the delivery disclosure. Market observers note that while 486,532 deliveries provided immediate equity relief, margin outcomes remain uncertain until official earnings disclosures. Furthermore, independent analyst Henry Soediarko noted that elevated capital expenditures tied to autonomous fleets continue to pressure underlying free cash flows.
Tesla trades around a high trailing price-to-earnings multiple of approximately 343, reflecting expectations far beyond automotive manufacturing. Retail order books from platforms like Pluang recorded profit-taking activity among 88% of transacting participants during the 4.65% pop. The heavy retail selling implies that experienced traders view delivery beats as liquidity events rather than confirmed structural trend reversals. A low automotive gross margin on October 21 could reverse recent trading advances.
Capital commitments dictate long-term valuation
Annual growth trajectory is achievable following third-quarter execution. Tesla delivered approximately 1,636,129 vehicles throughout 2025, leaving a fourth-quarter hurdle of about 311,448 units to produce positive year-over-year growth. Given that first-quarter deliveries represented the 2026 low at 358,023 vehicles, clearing this threshold remains feasible under stable supply conditions. Chief Financial Officer Vaibhav Taneja previously stressed that factory productivity optimization depends on securing specialized component chains.
Autonomous vehicle progress represents the true catalyst for sustained valuation multiples above $370.00. Institutional interest focuses on unsupervised Full Self-Driving milestones, robotaxi permissions across urban testing centers, and proprietary AI accelerator plants. However, the commercial timeline for unsupervised autonomy faces regulatory friction and rigorous validation burdens. Automotive cash generation must bridge the multi-year gap before recurring software revenue achieves critical corporate scale.

Traders should avoid market buy orders into elevated post-announcement implied volatility. Entering limit orders below immediate resistance and waiting for October 21 GAAP automotive margins represents prudent positioning. Specific conditions depend on individual brokerage guidelines and corporate filings, making earnings data the primary driver of forward equity trends.
Bottom line: Treat delivery beats as short-term volume stabilization until audited third-quarter earnings confirm whether aggressive price discounting damaged core automotive profitability.
ℹ️ This article was drafted with the help of an AI tool and reviewed/edited by a human before publishing. · Original: AdEngine-X
More from this author

📚 References
This list may include both live search sources the AI referenced while writing and public-data sources checked during fact verification. Please verify the original sources before citing or reusing.
0 Comments
Loading comments...